Key Takeaways
- Alternatives include downsizing to a smaller property, taking out a personal loan or credit line, securing a retirement interest-only mortgage, or receiving a family loan.
- Downsizing involves selling your current home and moving to a less expensive one, potentially freeing up cash without incurring loan costs, unlike equity release which allows you to stay in your home but accrues interest over time.
- Personal loans or credit lines, offering flexibility and possibly lower interest rates, but require monthly repayments which could be challenging on a fixed retirement income.
- The pros include potentially lower costs and avoiding the erosion of home equity, while cons may involve the impact on lifestyle, such as moving from your home in the case of downsizing, or the need for regular repayment schedules for loans.
- Considering family loans could offer lower costs and more flexible repayment terms, but it’s important to assess the impact on family relationships and ensure formal agreements are in place to avoid misunderstandings.
Before unlocking your home’s wealth, have you considered all the equity release alternatives out there?
From downsizing to diving into pension schemes, there’s more than one way to tap into your property’s potential.
[TOC]
Our expert financial team at TheEnquirer provides an in-depth look into these alternatives, delving into their practicality, potential advantages and drawbacks.
[CTA_1_CALL_BACK]
Why Look at Alternatives?
Exploring alternative routes isn’t just about finances; it’s about syncing choices with personal comfort, lifestyle aspirations, and long-term objectives.
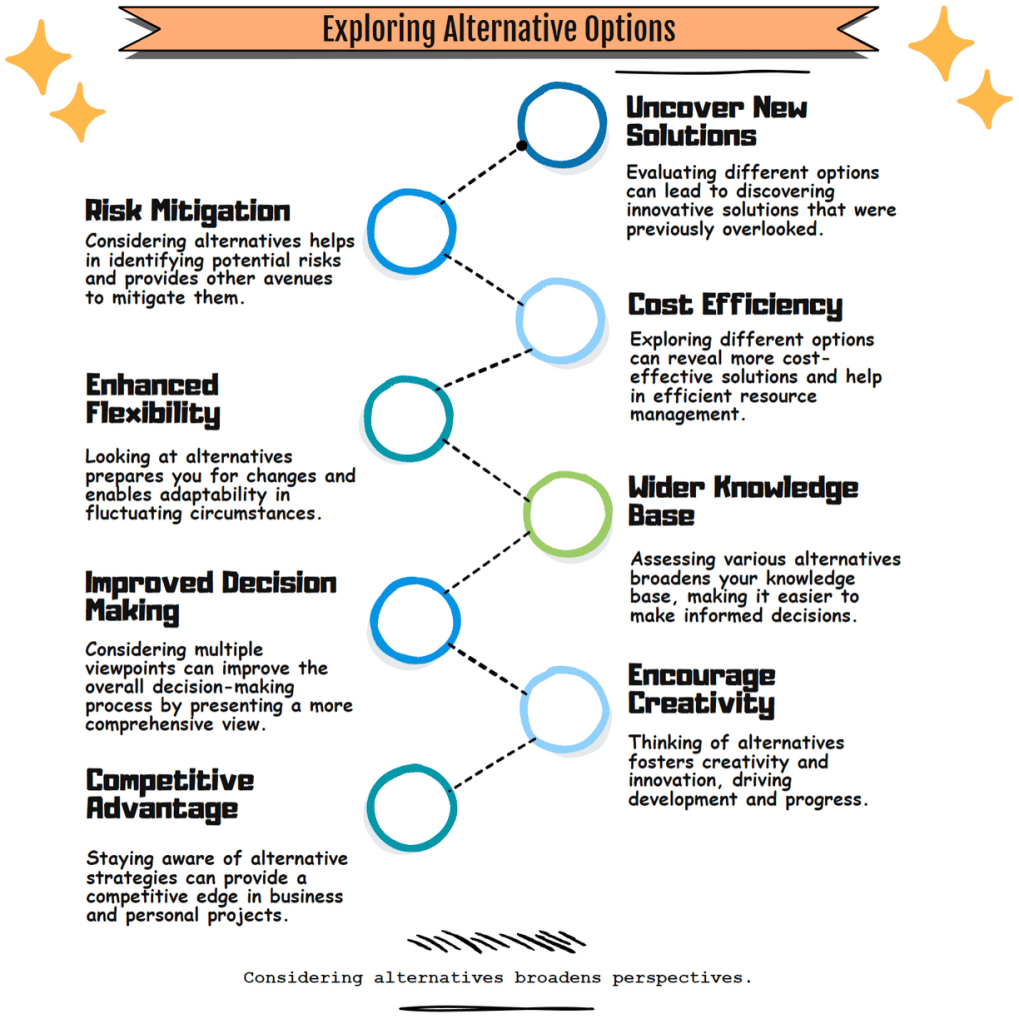
By delving into these options, you can pinpoint the solutions that best aligns with your existing circumstances and future goals.
Read On: Know More About Equity Release
11 Best Alternatives to Equity Release
#1. Downsizing
When you choose to downsize, you sell your current, larger property to purchase a smaller, more affordable one, releasing a substantial amount of money.
Along with the benefit of reduced maintenance costs and a potential lump sum, downsizing can also introduce you to new, vibrant communities.
However, leaving behind a cherished home can be emotionally challenging, and relocation costs can be substantial.
#2. Remortgaging
Remortgaging involves transferring your loan to a new mortgage deal, either with the same or a different lender, usually to procure better terms, reduce monthly payments, or access funds.
Keep in mind
While it can offer financial flexibility and possibly better interest rates, you must be cautious of early repayment charges and the costs of setting up a new agreement.
Learn More: Understanding Remortgaging in [SEO_DATE_YR]
#3. Secured Loans
Unlike a standard mortgage used to buy a home, a secured loan is an additional borrowing set against your property’s value.
These loans often have favourable interest rates, allowing you to retain your current mortgage deal.
However, there’s a substantial risk; failure to keep up with repayments could lead to repossession of your property.
#4. Pension Drawdown
Pension drawdowns allow you to withdraw sums from your pension pot while keeping the remainder invested.
This approach provides flexibility in accessing retirement funds. However, drawing too much too quickly can risk depleting your pension earlier than anticipated.
#5. Pension Lump Sum
Opting for a pension lump sum means accessing a large portion of your pension pot in one go.
This can offer immediate financial relief, but there might be tax implications based on the amount and your tax bracket.
Bear in mind, though
It’s crucial to manage this sum wisely to ensure sustained financial health.
#6. Savings & Investments
Proactively saving and investing a portoin of your income over the years can yield a robust financial safety net for the future.
By diversifying investments and periodically revisiting your financial portfolio, you can optimise returns and minimise potential risks.
#7. Rent Out a Room
In the UK, you can benefit from the Rent-a-Room scheme,1 allowing you to earn tax-free income by letting out furnished accommodation in your home.
While this can be a lucrative venture, you must be aware of your legal obligations and be prepared for the dynamics of sharing your living space.
#8. Deferred Payment Agreements
These agreements are arrangements typically made with local authorities, allowing you to use the value of your home to help cover care home costs.
This means
Instead of selling your home immediately to pay for care, you can defer or delay the sale until a later date.
The local authority essentially offers a “loan” against your home’s value to cover care costs, which is repaid when your home is sold or you pass away.
Although helpful in managing immediate care costs, it may significantly diminish the eventual value of your estate.
#9. Government Benefits & Grants
The UK government offers various aid programs, including Pension Credit2 and Housing Benefit.3
It’s crucial to understand the eligibility requirements and take full advantage of any benefits you might be entitled to.
#10. Family Assistance
Sometimes, your family can offer financial assistance as a gift or a loan.
Transparent communication is essential here, as well-defined terms can prevent future misunderstandings or familial strains.
#11. Lifetime ISA
A Lifetime ISA is a savings account designed for those under 40, providing a 25% government bonus on top of personal contributions.4
By saving consistently, you can maximise these bonuses, paving the way for considerable financial growth.
Common Questions
[CUSTOM_FAQ]
In Conclusion
While it’s a valuable option for many UK homeowners, equity release isn’t the only route to financial security during retirement.
There are a number of alternatives worth considering, such as downsizing, remortgaging, or even letting out a room in your home.
Each of these options has its own benefits and challenges that must be considered before making a decision.
By staying informed and consulting experts, you can navigate the landscape of equity release alternatives to secure a prosperous retirement.